
The physics of partner ecosystems
When you add a third partner, you change the whole system
There’s a concept in astrophysics called a Lagrange point.
Take two bodies in an orbital relationship, like the Sun and Earth. Together, their gravity and orbital motion create five mathematical locations called Lagrange points. Put a spacecraft near one of these points, and it can maintain a relatively consistent position in relation to both bodies with far less energy than it would require elsewhere.
The bodies are not stationary. They are moving constantly. But within that motion, there are points of equilibrium: places where the forces acting on an object align well enough to create stability and leverage.
Partnerships have Lagrange points, too.
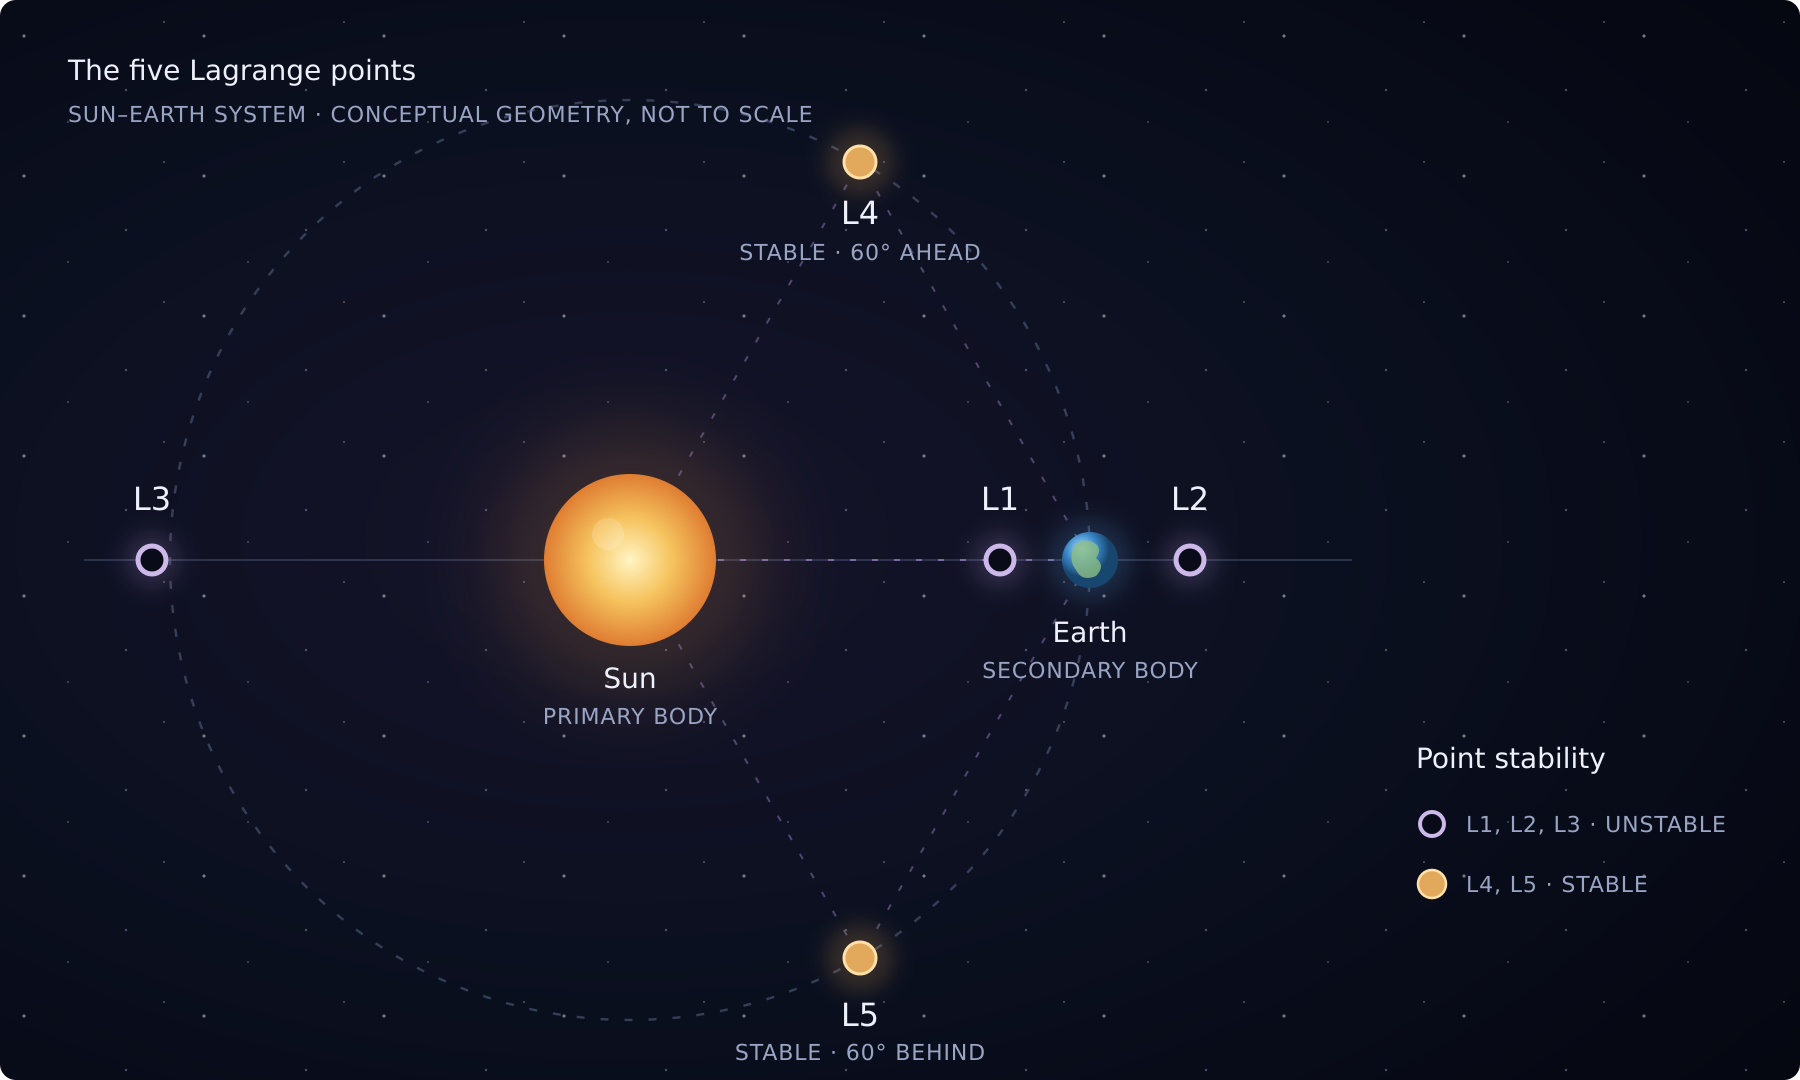
The five Lagrange points in the Sun–Earth system. Conceptual illustration, not to scale. Illustration by Megan Arnold, created with AI assistance using ChatGPT.
In a partnership between two companies, there are usually a few places where customer need, company strategy, product capability, seller motivation, and commercial value align. A shared customer segment. A complementary product integration. A marketplace motion that benefits both companies. A field play that gives each seller a reason to bring the other company into an account.
These are the points where the partnership can produce disproportionate value. The companies keep moving—their strategies change, leaders rotate, products evolve, budgets shift—but the motion can remain relatively stable because the forces between them are understood.
Then we add a third partner.
We often talk about this as though we are simply expanding the opportunity. One company brings the platform, another brings the application, and a third brings the services required to implement it. Each participant adds capability, reach, credibility, or access to the customer. The combined value proposition becomes stronger.
At least, theoretically.
Because adding a third partner does not simply add another participant. It changes the physics of the system.
Three partners create more than one new relationship
With two companies, there is one bilateral relationship to manage. With three, there are three:
- Company A and Company B
- Company A and Company C
- Company B and Company C
And then there is the collective relationship among all three.
Each bilateral relationship may have its own history, economics, executive sponsorship, product dependencies, sales incentives, and definition of success. A decision that strengthens one relationship can destabilize another. A roadmap change at one company can alter the value proposition for all three. A seller incentive introduced by one partner can redirect attention away from the collective motion. A disagreement about customer ownership can stop the entire system at the moment it is supposed to create value.
The third partner has not just made the partnership bigger. It has introduced new forces and feedback loops.
This distinction matters because the way we plan multipartner growth often assumes that value is additive. If Partner A brings a certain set of customers and capabilities, and Partner B brings another, adding Partner C should increase the opportunity again.
But the size of the opportunity is only one part of the commercial equation:
Expected revenue = market opportunity × probability of execution × value captured
A third partner can increase the potential market opportunity while simultaneously reducing the probability of execution. The total value available may be larger, but there are now more dependencies, handoffs, approvals, incentives, systems, and decisions that must align before any of that value becomes revenue.
That is the multipartner paradox: the same partner that expands the opportunity can also make the opportunity harder to realize.
The strategy usually looks better than the system beneath it
Imagine a joint go-to-market motion among a cloud platform, an independent software company, and a services partner.
The customer story is compelling. The platform provides the infrastructure. The software company provides a specialized solution. The services partner helps the customer implement it and achieve the promised business outcome. Together, the companies can solve a larger and more consequential problem than any one of them could solve alone.
The executive slide practically writes itself.
Then the work begins.
Which accounts are the companies targeting? Do all three define the ideal customer the same way? Which sales representatives cover each account? Who already has the strongest relationship? Who makes the introduction? Who leads the customer conversation?
If the companies launch a campaign, who pays for it? Who builds it? Whose brand leads? Where do the responses go? Whose business development representatives qualify them—and according to whose criteria? Can the resulting customer data legally and technically move between all three organizations?
If a lead becomes an opportunity, which company records it? How do the other two know it is progressing? Which sellers receive credit? Who owns the next action? Who transacts? Who implements? Who is accountable for adoption after the contract is signed?
These questions can be dismissed as execution details. They are not peripheral to the strategy. They are the mechanisms through which the strategy either becomes revenue or does not.
A campaign can generate hundreds of responses and still fail commercially because no one designed the handoff between companies. A customer opportunity can exist in three CRM systems under three different names and still have no clearly accountable owner. Three sellers can all support the same strategic motion while each waits for someone else to initiate it.
The campaign did not necessarily fail. The system around the campaign failed.
Not every point of alignment is stable
The astrophysics metaphor is useful for another reason: not all Lagrange points are equally stable.
In partner ecosystems, some forms of alignment naturally reinforce themselves. If the solution solves a real customer problem, the commercial path is clear, sellers receive meaningful credit, and each company benefits from the customer’s success, the motion may continue with relatively little intervention.
Other motions only appear stable because partner and marketing teams are constantly correcting them. Someone manually reconciles the account lists. Someone tracks down the sales representatives. Someone carries customer context from one system to another. Someone schedules the meeting, follows up on the action items, resolves the attribution dispute, and reminds every participant why the work matters.
Remove that person, and the motion drifts.
This does not mean the opportunity is unworthy. But it does mean we should distinguish between a motion that is structurally aligned and one that is being held together through continuous human effort. They have different costs, risks, and potential to scale.
One of the most important questions in partnership strategy, then, is not simply, “Where can we create value together?” It is:
What would have to remain true across all participating companies for that value to be created repeatedly?
That question shifts the work from planning an activity to designing a system.
The customer is the center of gravity
There is also a danger in becoming so absorbed in the complexity between partners that we lose sight of why the ecosystem exists.
The customer does not care that three companies have different fiscal calendars, sales territories, privacy policies, CRM platforms, reporting models, or internal definitions of an influenced opportunity. The customer experiences only the collective result.
Did the companies understand the problem? Did they present one coherent solution? Did they know what the customer had already shared? Was there a clear next step? Could the customer buy, implement, and adopt the solution without becoming the project manager for the partnership?
The customer journey is where the internal physics of the ecosystem becomes visible, much as celestial bodies reveal the otherwise invisible forces acting between them.
If three companies promise an integrated outcome but deliver a fragmented buying experience, the solution is not truly integrated from the customer’s perspective. The customer ends up absorbing the coordination costs the partners failed to resolve.
That friction has direct commercial consequences: longer sales cycles, lower conversion, stalled procurement, weaker adoption, and fewer expansion opportunities. Conversely, when the companies make their boundaries nearly invisible to the customer, orchestration becomes a source of competitive advantage.
Partner leaders are designing systems of work
Multipartner growth cannot be achieved by stacking several bilateral go-to-market plans together. The collective system has to be designed intentionally.
That means designing more than the market message. It means designing how decisions are made, how information moves, how accounts are prioritized, how sellers engage, how customer context survives handoffs, how incentives reinforce the desired behavior, and how success is measured across organizational boundaries.
The highest-leverage work may happen in places that never appear in the launch announcement: the account-mapping process, the lead-routing agreement, the shared opportunity stages, the seller-credit model, the governance mechanism, or the decision about who owns the customer’s next step.
Those operational seams are where theoretical ecosystem value becomes—or fails to become—customer value and revenue.
The future of partner leadership is not simply managing a larger portfolio of relationships. It is learning to engineer dynamic systems among companies that continue moving independently but must create a coherent outcome together.
Because when you add a third partner, you do not merely expand the partnership.
You change its physics.
